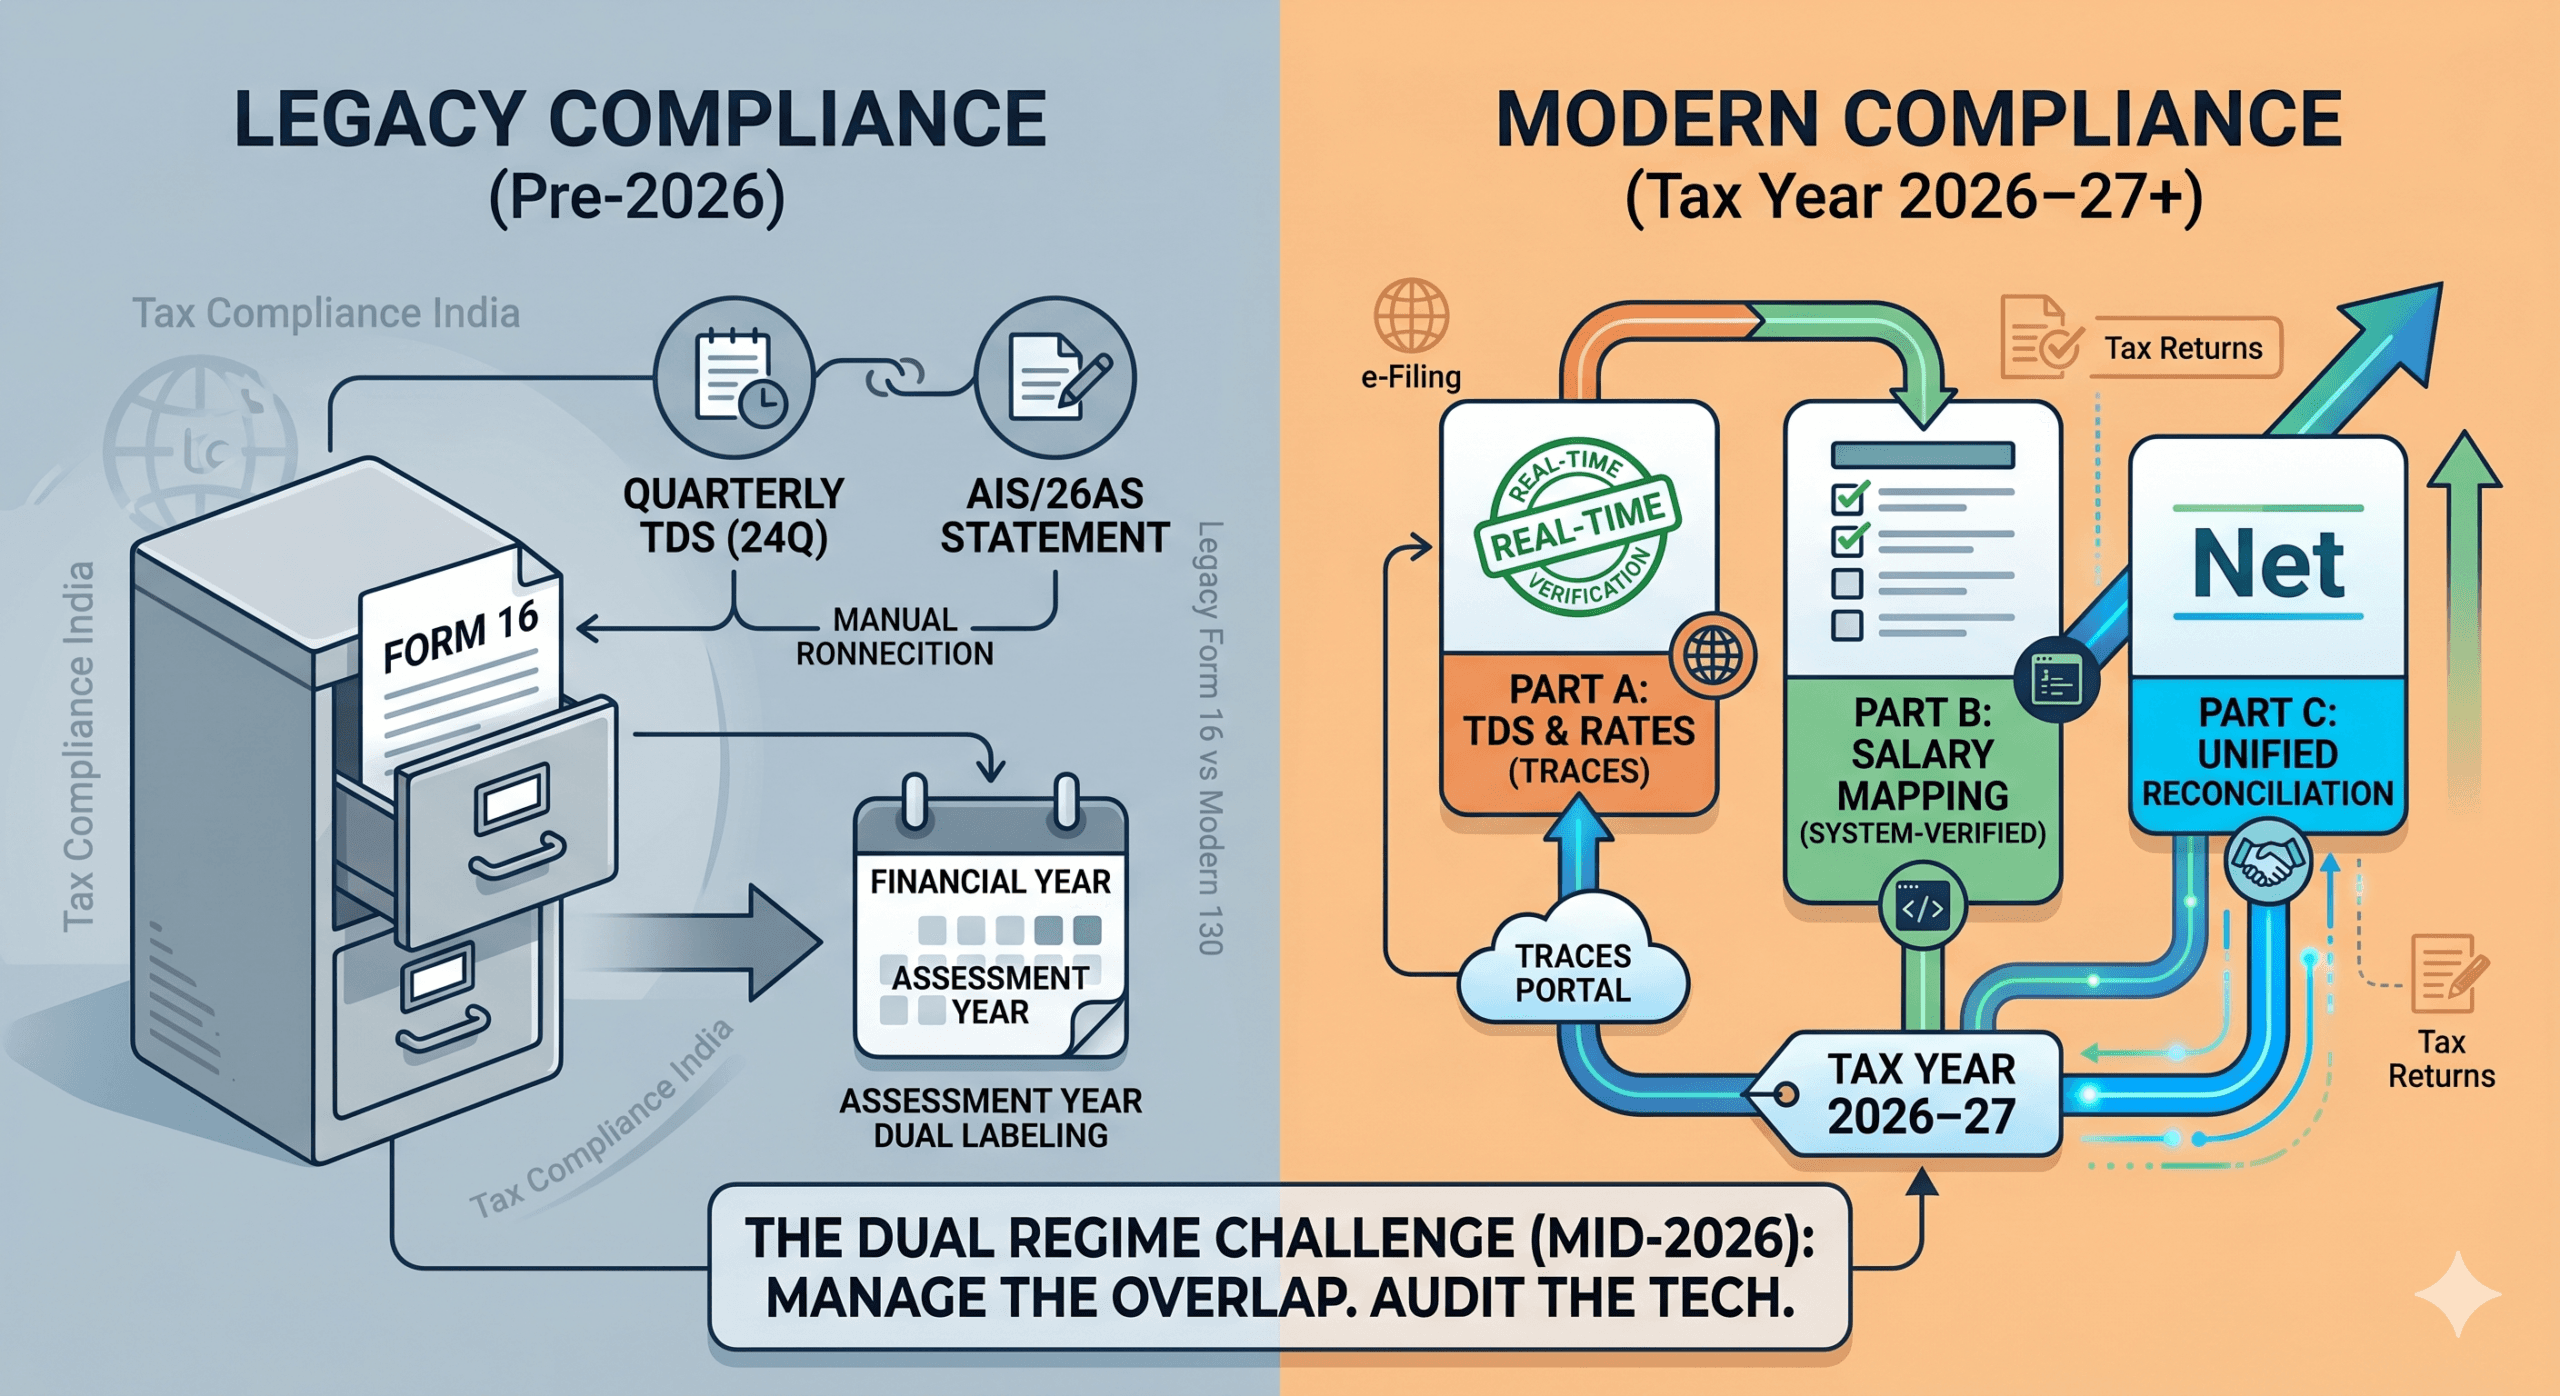
Corporate tax structuring for foreign subsidiaries in India centers on electing Section 115BAA of the Income Tax Act, which establishes a concessional base tax rate of 22% (effective rate 25.17% inclusive of surcharge and cess) for domestic companies established via India company setup services. Opting for Section 115BAA completely exempts the subsidiary from Minimum Alternate Tax (MAT), contrasting sharply with the 40% base tax rate (plus surcharge and cess) levied on foreign branch offices, supported by ongoing India accounting and corporate tax services.
As detailed in our foundational roadmap, the UK Founder’s Blueprint to Setting Up Operations in India, entity incorporation requires navigating an intricate matrix of domestic tax incentives, transfer pricing rules, and cross-border profit repatriation pathways. For UK Chief Financial Officers and corporate tax controllers, structuring an Indian corporate vehicle correctly from inception prevents unexpected tax leakages and optimizes group effective tax rates (ETR) when consolidating into UK statutory accounts. Backed by our cross-border tax advisory practice, this master advisory delivers the quantitative and legal blueprint for corporate tax structuring in India.
1. Corporate Tax Rate Comparison: Domestic Subsidiary vs. Foreign Branch
Foreign corporations establishing operations in India must evaluate the stark statutory tax differential between an Indian incorporated private limited company (WOS) and an unincorporated foreign branch or project office:
| Tax Parameter | Domestic Subsidiary (Sec 115BAA) | Domestic Subsidiary (Old Regime) | Foreign Branch / Project Office |
|---|---|---|---|
| Base Corporate Tax Rate | 22.00% | 25.00% (Turnover ≤ ₹400 Cr) / 30% | 40.00% |
| Mandatory Surcharge | Flat 10.00% (irrespective of income) | 7% (Income > ₹1 Cr) / 12% (> ₹10 Cr) | 2% (Income > ₹1 Cr) / 5% (> ₹10 Cr) |
| Health & Education Cess | 4.00% on tax plus surcharge | 4.00% on tax plus surcharge | 4.00% on tax plus surcharge |
| Effective Corporate Tax Rate | 25.17% | 26.00% – 34.94% | 41.60% – 43.68% |
| Minimum Alternate Tax (MAT) | EXEMPT (Section 115JB(5A)) | Applicable at 15% base rate | Applicable (Subject to treaty carve-outs) |
| Allowable Deductions / Holidays | No Chapter VI-A deductions (except 80JJAA) | Can claim SEZ (Sec 10AA) & R&D credits | Restricted head office expense deductions |
2. Minimum Alternate Tax (MAT) Relief
Under Section 115JB, companies operating under the traditional corporate tax regime must pay MAT at 15% (plus surcharge and cess) on "book profits" if their regular corporate tax liability falls below this threshold. This created severe cash flow distortion for high-growth tech firms carrying heavy depreciation or stock compensation charges.
By electing Section 115BAA via Form 10-IC on or before the due date for filing the return of income under Section 139(1), a foreign subsidiary is permanently exempted from MAT provisions under Section 115JB(5A). Payline's corporate tax practice models and executes this election during first-year filings.
3. Profit Repatriation Pathways to the UK Parent
Foreign investors have three primary legal mechanisms to repatriate post-tax profits from an Indian subsidiary back to the UK parent corporation:
- Dividend Distribution: Following the abolition of the Dividend Distribution Tax (DDT), dividends are taxable in the hands of the shareholder. Under Indian domestic law, dividends paid to a non-resident parent company are subject to 20% withholding tax under Section 195. However, under Article 10 of the India-UK DTAA, the withholding tax rate is capped at 10% or 15% (subject to beneficial ownership and holding thresholds), provided the UK parent furnishes a valid Tax Residency Certificate (TRC) and electronic Form 10F prepared by our tax advisory team.
- Management Fees & Royalties (Article 12): Arm’s length fees for technical services (FTS) or IP licenses. Cross-border payments are subject to a 10% withholding tax under the treaty. Must be supported by robust transfer pricing documentation. Read our compliance guide in Transfer Pricing and India–UK Double Taxation Avoidance Agreement (DTAA).
- Capital Reduction / Share Buyback: Under Section 115QA, share buybacks by unlisted domestic companies are subject to a buyback tax of 20% (plus 12% surcharge and 4% cess = 23.296%) in the hands of the company, with proceeds exempt in the hands of the UK shareholder under Section 10(34A).
Frequently Asked Questions (Corporate Tax Structuring)
Can a newly incorporated Indian subsidiary opt out of Section 115BAA once elected?
No. Under Section 115BAA(5), once a domestic company exercises the option to be taxed under the concessional 22% regime for any financial year, the option cannot be subsequently withdrawn for that or any subsequent year.
What is Section 80JJAA and does it apply under Section 115BAA?
Section 80JJAA provides an exceptional tax deduction equal to 30% of additional employee cost incurred for three consecutive assessment years. It is one of the very few tax incentive deductions explicitly retained and permitted under the Section 115BAA corporate tax regime, offering substantial tax savings for scaling Indian tech hubs.
Optimize Your Indian Corporate Tax Architecture
Payline’s cross-border tax practice handles corporate entity structuring, Section 115BAA filings, dividend withholding certifications, and DTAA tax optimization.
Schedule a Corporate Tax Advisory Session